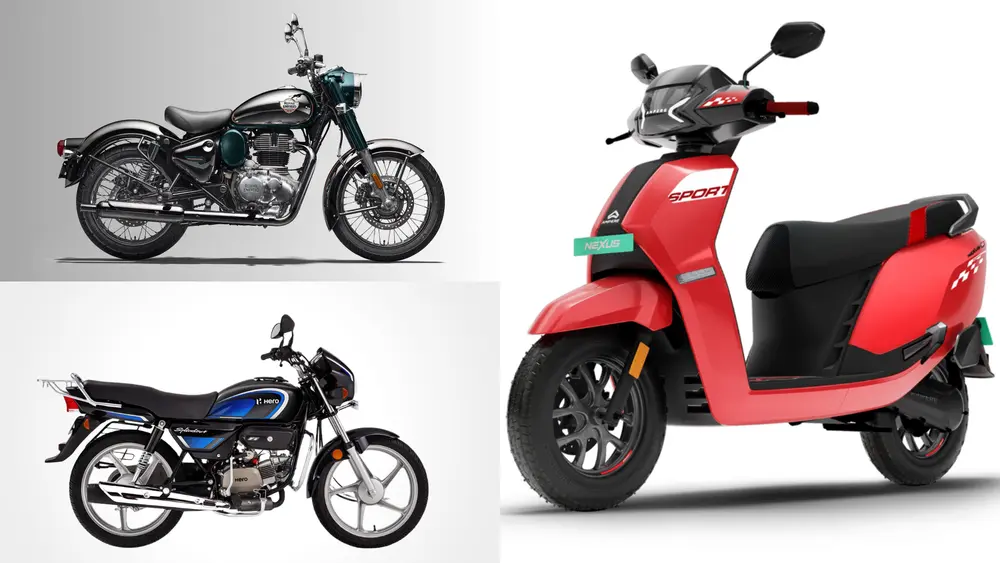
Quick Read - India's two wheeler market saw different sales trends across segments in September 2026. The mass-market two wheeler segment sold 16,01,295 units, premium two wheelers sold 1,07,213 units, and EVs sold 60,675 units. All segments witnessed an improvement from August 2026.
Budget / Mass-Market Makers
| Maker | Sep 2026 | Aug 2026 | MoM | Jan–Sep 2026 |
|---|---|---|---|---|
| Hero MotoCorp | 4,33,968 | 4,15,100 | +4.5% | 43,64,104 |
| Honda (HMSI) | 4,67,687 | 4,49,091 | +4.1% | 42,31,274 |
| TVS Motor | 3,64,261 | 3,55,639 | +2.4% | 33,09,225 |
| Bajaj Auto | 1,65,981 | 1,58,155 | +4.9% | 17,26,324 |
| Suzuki Motorcycle | 1,01,586 | 1,04,765 | −3.0% | 9,17,461 |
| India Yamaha | 64,046 | 62,600 | +2.3% | 5,85,074 |
| Piaggio Vehicles | 3,766 | 3,626 | +3.9% | 30,329 |
| Segment Total | 16,01,295 | 15,48,976 | +3.4% | 1,51,63,791 |
September was a bounce-back month for the volume players after a weak August.
The whole segment added about 52,000 units over August, and the recovery was broad six of seven makers grew.
But the month-on-month gain hides the bigger story: the segment is still well below where it started the year. January did 17.5 lakh, September did 16.0 lakh, so mass-market volumes are down roughly 8.5% over nine months.
March was the high point at about 18.3 lakh (year-end push and pre-price-revision buying), then volumes slid every month through August, which is normal the monsoon and the inauspicious Shraddh fortnight always flatten commuter demand.
Honda is the standout: it is the only top-three maker that has essentially held its January level, and in September it outsold Hero by about 34,000 units. Hero is growing month-on-month but has lost the most ground since January. Bajaj is the weakest trendline in the group, down from 2.05 lakh in January to 1.66 lakh in September, roughly a 19% erosion.
Looking ahead, October should be the strongest month of 2026 for this segment Navratri starts in mid-October and Diwali falls in early November, so almost the entire festive window sits in Oct–Nov this year, and September's uptick is largely dealers stocking up for it.
Expect October to land in the 17.5–18.5 lakh range, November to hold up, then a sharp drop in December as dealers clear inventory and buyers wait for new-year registrations.
Also Read - September 2026 Car Sales As Per Vahan
Premium Makers
| Maker | Sep 2026 | Aug 2026 | MoM | Jan–Sep 2026 |
|---|---|---|---|---|
| Royal Enfield | 1,01,831 | 96,721 | +5.3% | 8,93,829 |
| Classic Legends (Jawa/Yezdi/BSA) | 4,568 | 4,360 | +4.8% | 42,561 |
| India Kawasaki | 403 | 425 | −5.2% | 3,846 |
| BMW India | 378 | 410 | −7.8% | 4,034 |
| Ducati India | 33 | 34 | −2.9% | 353 |
| Segment Total | 1,07,213 | 1,01,950 | +5.2% | 9,44,623 |
Premium grew faster than the mass market in September, up 5.2%, and that growth is almost entirely Royal Enfield it is 95% of this segment's volume, so the segment basically moves when Royal Enfield moves.
RE crossed back above the one-lakh mark for the first time since March, which matters because it signals the premium buyer is coming back into showrooms ahead of the festive season; a 350cc+ purchase is a discretionary, financed decision, so it clusters around festive and bonus months far more tightly than a commuter bike does.
Classic Legends is quietly stable at roughly 4,500 a month, holding its small niche without breaking out. The imported brands moved the other way: BMW, Kawasaki and Ducati all declined, but these are three-digit volumes where ten or twenty units swing the percentage, so the drops are noise, not trend.
Note that KTM and Triumph volumes sit inside Bajaj's number, and Harley's inside Hero's.
For October–November, expect RE to push toward 1.10–1.20 lakh on festive dispatches, which would make Q4 its strongest quarter of the year.
Also Read - Honda CB350C Launched in India at Rs 2 Lakh, Gets New Colours and Graphics
EV Makers
| Maker | Sep 2026 | Aug 2026 | MoM | Jan–Sep 2026 |
|---|---|---|---|---|
| Ather Energy | 30,479 | 29,068 | +4.9% | 2,61,315 |
| Ola Electric | 13,449 | 13,941 | −3.5% | 1,07,857 |
| Greaves Electric Mobility | 9,314 | 8,623 | +8.0% | 71,880 |
| River Mobility | 5,549 | 5,216 | +6.4% | 38,714 |
| Simple Energy | 1,349 | 1,664 | −18.9% | 11,796 |
| Ultraviolette | 535 | 611 | −12.4% | 4,118 |
| Segment Total | 60,675 | 59,123 | +2.6% | 4,95,680 |
This is the only segment that is meaningfully bigger than it was in January about 40,500 units then versus 60,675 in September, roughly 50% growth in nine months, against an ICE market that shrank.
Ather is now the clear pure-play leader at 30,479 units, more than twice as much of Ola, and it has held the 29,000–31,000 band for four straight months, which is the more important signal: it has moved from spiky growth to a stable, predictable base.
Ola is the mirror image it peaked at 16,294 in June and has fallen every month since, down to 13,449, so it is losing share inside a growing segment, which is the hardest position to recover from. Greaves (Ampere) is the quiet gainer, up 8% and now the clear number three.
TVS iQube, Bajaj Chetak and Hero Vida are counted inside their parent companies' ICE numbers and add those and true electric share is closer to the 6–8% range.
Also Read - Honda QC3 Launched At Rs 1.35 Lakh With 145km Range, 5-inch TFT
For October onward, expect EVs to grow faster than ICE in percentage terms: festive demand plus year-end discounting should push the pure-play group past 65,000 units in October, with Ather consolidating and Ola's decline the main thing to watch.
Source: Vahan
Table of Contents
- Budget / Mass-Market Makers
- Premium Makers
- EV Makers
Join the Conversation
Trending
TVS Raider Price Hiked By Up To Rs 2,600, Now Starts At Rs 84,460
TVS has increased the Raider’s prices by up to Rs 2,600 in India, with the range now starting at Rs 84,460. The TFT Dual Disc variant gets the biggest hike, while the Doctor Doom edition remains unchanged.
Arjun Nair
October 1, 2026
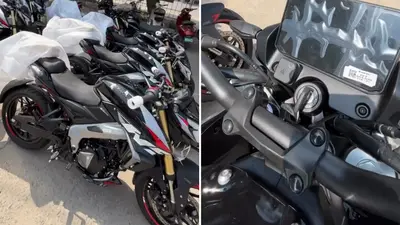
Updated Bajaj Pulsar NS125 Spotted With LCD Display and Fresh Graphics
The updated Bajaj Pulsar NS125 has been spotted at dealerships with a new LCD display and fresh colour options ahead of an imminent launch. A higher TFT variant is expected too, with prices likely to rise from Rs 99,622.
Anmol Kumar
September 29, 2026
A Full List Of E20 Compliant Bikes and Scooters in India
Here is a list of every bike/scooty maker with E20 compatible 2-wheeler in their portfolio in 2026
Salil Kumar
September 28, 2026
Featured
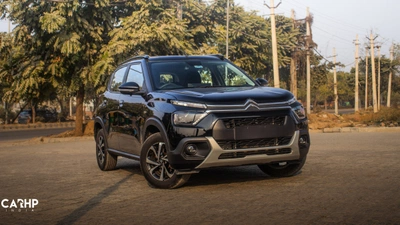
Citroen C3 Review: Who Should Consider This Car?
A few days ago, I took the Citroen C3X out for a spin in the city and on the highways. I travelled long distances and checked its fuel efficiency, features, comfort, and other factors. Today, I’ll briefly share my overall experience with the C3X and will tell you whether you should consider it or not and which is the most value-for-money variant of the lot.
Vatsal Agrawal
May 19, 2026
Tesla Finally In India Officially. Why Now And What Does It Mean For EVs?
The much-anticipated 2025 Tesla Model Y has officially arrived in India, marking a pivotal moment for the nation's burgeoning electric vehicle market. Launched on July 15, 2025, the Model Y Juniper facelift offers cutting-edge technology, impressive range, and signature Tesla performance. Positioned as a premium electric SUV, its entry will intensify competition and reshape consumer expectations for EVs across the subcontinent.
Charan Narain
July 17, 2025
Here Are 10 Things The Harrier.EV Offers That The Mahindra XEV 9E Doesn't
The Harrier.EV is an incredible new offer from Tata. Its most popular competitor would be the Mahindra XEV 9E, priced similarly. With these two incredible offerings from home grown brands available, here is a list of everything the Harrier.EV offers that the XEV 9E doesn't.
Charan Narain
June 13, 2025
Write a comment
Comments
No comments yet. Be the first to comment!